

Not long ago, a borrower came to me with a deal that every lender he'd talked to had already passed on. The property was fine. His numbers were fine.
The loan was just too small. He needed a small hard money loan TN investors know is hard to place, and nobody would give him one.
Key Takeaways
- A $40,000 rehab loan sat below most lenders' minimums, including ours at $50,000
- We restructured it into a $70,000 loan using a rehab budget plus an earnout draw
- The borrower ended up better capitalized than if we'd just said yes to the original ask
- Rural Tennessee properties in small towns are lendable to us when most others won't go there
- We've funded 300+ loans this way, many of them starting with a borrower nobody else called back
In This Article
- The Deal on Paper
- Why a Small Hard Money Loan in TN Is Hard to Place
- The Structure: Rehab Budget Plus an Earnout
- Why the Borrower Ended Up Better Off
- A Small Tennessee Town Is Not a Deal Killer
- If Your Deal Is "Too Small," Call Us Anyway
- Frequently Asked Questions
The Deal on Paper
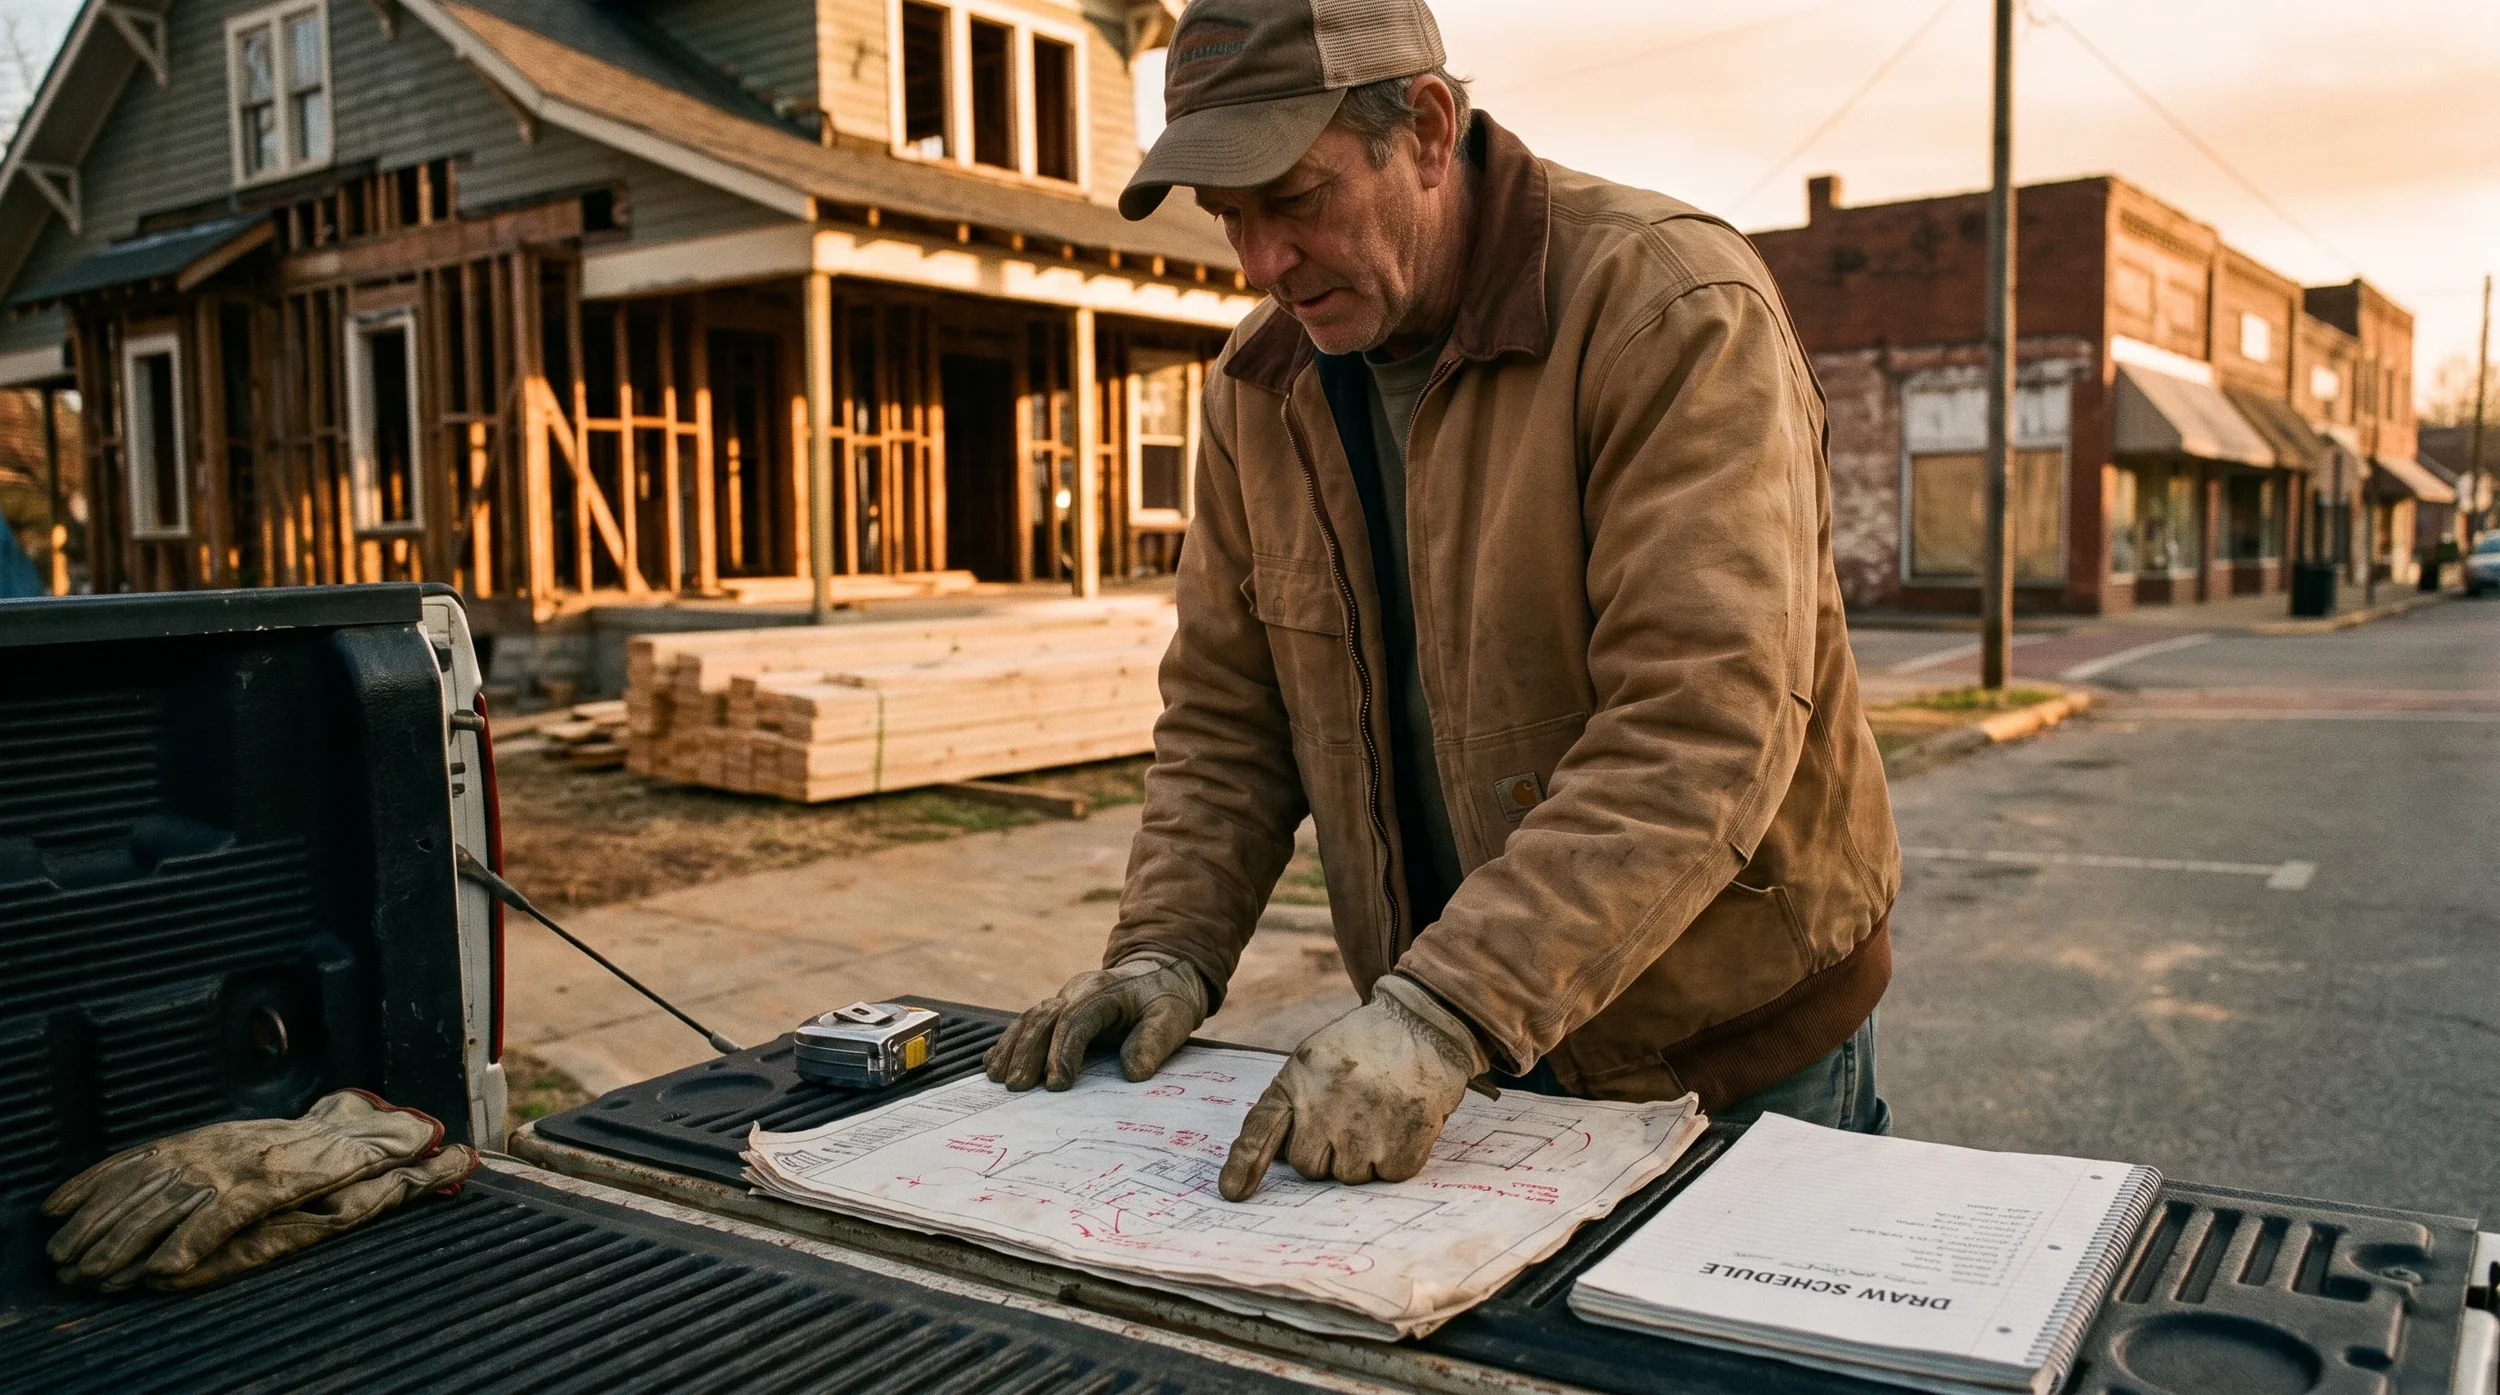
He owned a rural Tennessee property free and clear. He'd bought it for around $100,000, needed about $40,000 to remodel it, and finished, it would be worth somewhere between $150,000 and $200,000. His exit was simple: sell the property.
On paper, this is a clean deal. Strong equity, a clear exit, and a borrower who already owned the asset outright. The problem wasn't risk.
The problem was the size of the ask.
Nobody would fund it. So instead of adding our no to the pile, we called him back and asked a question he wasn't expecting: what if we lent him more money than he asked for?
Why Getting a Small Hard Money Loan TN Borrowers Need Is Hard to Place
Hard money loans cost money to make, no matter the size. Underwriting, title work, our opinion of value, draws, servicing: most of that costs roughly the same whether the loan is $300,000 or $40,000. Small loans are also short loans, and there's less room for the interest and points to cover the work of originating them.
That's why just about every private money lender in this space has a floor. Ours is $50,000. At $40,000, this deal sat under it, and not by a little.
The no's he was collecting were honest ones. The loan he was asking for didn't make sense as a straight loan. Most lenders stop there.
We've never liked stopping there.
Why Institutional Lenders Say No Faster
National and institutional lenders operate on guidelines written in a conference room, not on a specific property in a specific town. A $40,000 ask in rural Tennessee hits two red flags at once: the dollar amount and the zip code.
Many institutional lenders write population minimums right into their guidelines. If the town has under 20,000 people, the deal is dead before anyone looks at the house. Add a loan amount below their floor, and you're collecting rejections before you even get to a human.
That's not a knock on those lenders. Their model just isn't built for this. Ours is.
The Structure: Rehab Budget Plus an Earnout
So I called him and said, let's get creative. What if I give you more remodel money than you need? He wasn't expecting that question, but he listened.
Because the borrower owned the property free and clear, we took a first lien on the asset to secure the full loan, which is what made the structure clean for both sides. The loan came in two pieces, and it's worth understanding how each one worked.
Piece One: The Standard Rehab Draw
The first $40,000 worked like any rehab budget we fund. He itemized the scope of work, and as the work got completed, he sent us video of it. We reimbursed him, with draws funded the next day.
No invoice packets, no lien releases, no waiting on a third-party inspector to fly out and look at a bathroom. Video draws are how we work on every loan, big or small.
Piece Two: The Earnout Draw
The second piece is where other lenders aren't set up to go. When he finished the house, we funded a final completion draw of about $30,000. We call it an earnout draw internally: a lump-sum draw funded at completion, after the rehab work is done and documented.
Together, the loan came to roughly $70,000. That's above our minimum for a small hard money loan TN borrowers typically struggle to place, so the deal worked for us. And it worked out better for him than the $40,000 he originally asked for.
If you're sitting on a small hard money loan TN deal that looks similar, this structure may apply to yours too.
Why the Borrower Ended Up Better Off
The earnout did two things for him. First, it replenished his cash while he waited for the house to sell. A remodel eats working capital fast, and smaller markets move slower than Knoxville: the gap between finished and sold can stretch a few months.
He hadn't thought about borrowing more than he needed. His focus was keeping the loan small and the cost down. When we laid out the earnout structure, he said he'd never been offered that before.
He used the completion draw to cover holding costs and put a deposit on his next property before this one even sold.
Second, it put him in position to buy his next property. He came in asking for $40,000 and left with the remodel funded plus capital in the bank to keep investing.
We're a direct balance-sheet lender. Chris and Flynt are the decision makers, and there's no one above us. No capital partner had to approve this structure.
We looked at the deal, saw a clean asset with strong equity, and built something that worked. That's what finding a path on a small hard money loan TN request actually looks like when the lender has their own capital and the authority to use it.
A Small Tennessee Town Is Not a Deal Killer
There's a second layer to this story, and it's where the property sat. A lot of Tennessee isn't lendable to a lot of lenders. Outside of Knoxville, Chattanooga, and the Tri-Cities, this state is mostly mid-size cities surrounded by small pocket towns.
Athens, Oliver Springs, Harriman, Rockwood: those little finger markets 30 to 50 minutes outside Knoxville are places we fund deals every month. Most institutional lenders won't touch them. We drive out to them.
Our rule of thumb is simple. If it's surrounded by other houses in one of these smaller places, kind of near the epicenter of that small town, we'll do it. If it's out in the true boonies, we won't.
But a rural town is not the same as the middle of nowhere.
When the Remodel Budget Exceeds the Purchase Price
Small towns also mean small price tags, and that shapes our loans in a way most lenders aren't comfortable with. A lot of our deals end up with a remodel budget bigger than the purchase price. For most lenders, that ratio alone kills the deal.
For us, it's routine. A property bought for $80,000 with a $100,000 rehab budget, heading toward a $250,000 ARV: we've done that structure more than once. The math on the exit is what matters, not the ratio of cost buckets.
We fund up to 70% of ARV on fix and flip deals. On this deal, the numbers sat well inside that range, which is part of why the creative structure made sense from day one.
If Your Small Hard Money Loan TN Deal Got Rejected, Call Us
If you've been shopping a small hard money loan TN deal around and nobody will fund it, call us. We're a direct private money lender and the money we lend is ours. There's no committee above us and no capital partner who has to sign off on a structure they've never seen before.
A small hard money loan TN investors can't place elsewhere is exactly the kind of deal we want to hear about.
Either we tell you honestly what your deal would need to work, or we restructure it the way we did this one and you're on to the next property. We've funded 300+ loans and more than $53 million this way, and plenty of them started with a borrower nobody else would call back.
Rates start at 9.99% and go to 12.99% depending on credit, location, experience, and income. Points run 2 to 3. Standard close is 7 to 14 days.
And if you're a repeat borrower, the loyalty program brings costs down over time: by deal four with us, you're at 9.99% plus 2 points, and it keeps getting cheaper from there.
What We Actually Need to Look at a Deal
We're not a paperwork-first shop. If you're sitting on a small hard money loan TN deal that got turned down somewhere else, call us, tell us the property, the purchase price, what the remodel costs, and what you think it sells for. We'll tell you in plain terms whether we can do something with it.
We're not looking for a resume. First-time flipper in Harriman with a clean deal: call us. Experienced investor in Oliver Springs who got declined for a deal structure a national lender had never seen before: call us.
We've been active real estate investors ourselves since 2017, and we underwrite from that perspective, not from a checklist.
Frequently Asked Questions
What is the minimum loan amount for a small hard money loan in TN at Approach Lending?
Our minimum is $50,000, though exceptions are possible. In the deal described here, the borrower's original $40,000 ask sat below our floor, so we restructured it into a $70,000 loan using a rehab draw plus an earnout. That brought it above our minimum and worked better for the borrower too.
Do you fund hard money loans in small Tennessee towns and rural areas?
Yes. We fund deals in tertiary markets that most institutional lenders won't touch, including Athens, Oliver Springs, Harriman, and Rockwood. Our rule is that if the property is surrounded by other houses near the center of a small town, we'll look at it.
True rural boonies we pass on, but a small town is not the same thing.
What is an earnout draw, and how does it work in a rehab loan?
An earnout draw is what we call the final draw we fund when the rehab is complete. It's our internal term for a lump-sum completion draw funded after the work is finished and documented. In the deal in this post, the borrower received $40,000 in standard rehab draws as work was completed, then a $30,000 completion draw at the end.
It replenished his working capital while he waited for the property to sell and left him positioned to buy his next deal.
How fast can you close a small hard money loan in Tennessee?
Our standard close is 7 to 14 days. We ask for 14 and often finish in 10. For true rescue scenarios where a borrower's prior lender backed out, we have a documented 24 to 48 hour close, but that's a rescue capability, not the standard timeline.
Do you fund deals where the remodel budget is bigger than the purchase price?
Yes, and it comes up often in smaller Tennessee markets where purchase prices are low. Most lenders won't go there. We look at the ARV and the exit, not the ratio of the rehab budget to the purchase price.
We fund up to 70% of ARV on fix and flip deals, and we've closed plenty where the renovation cost exceeded what the borrower paid for the property.